Quick answer
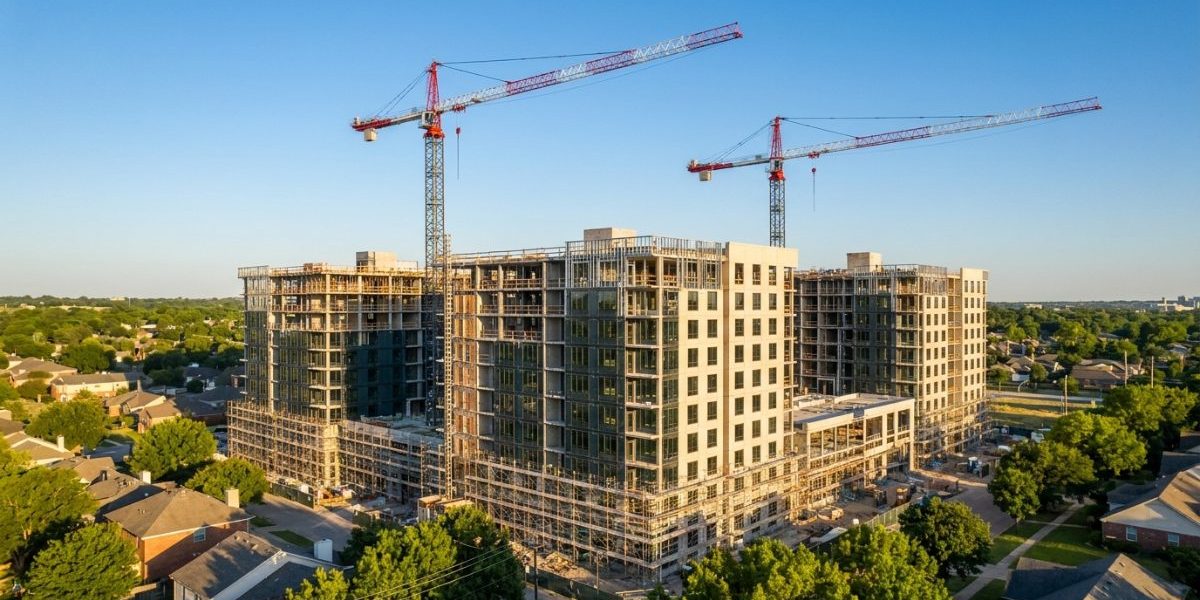
Build-to-rent (BTR) construction loans in Georgia finance the ground-up development of single-family, townhome, or cottage-style rental communities — covering land, horizontal site work, and vertical construction in inspected draws — and are repaid by a takeout loan once the community is built and leased. Because Georgia is a nonjudicial, first-Tuesday foreclosure state with no post-sale redemption, construction lenders view Georgia collateral as enforceable, which supports competitive leverage for experienced Atlanta-metro developers. Bancaverse arranges the construction loan and lines up the DSCR portfolio or agency takeout so the exit is underwritten before the first draw.
Key takeaways
- BTR is underwritten as a rental, not a subdivision — the lender sizes the construction loan to the stabilized rental value and the takeout it will support, not to lot sales.
- Horizontal and vertical are separate risk phases — land, entitlements, and site work are funded first, with vertical draws released against inspected progress and lien waivers.
- Georgia’s 2021 lien-waiver law matters on every draw — waivers now release only lien and bond rights, and a claimant has 90 days to file an affidavit of nonpayment [3].
- Plan the takeout at the term sheet stage — a DSCR portfolio loan or agency loan on the completed community is what makes the construction loan fundable.
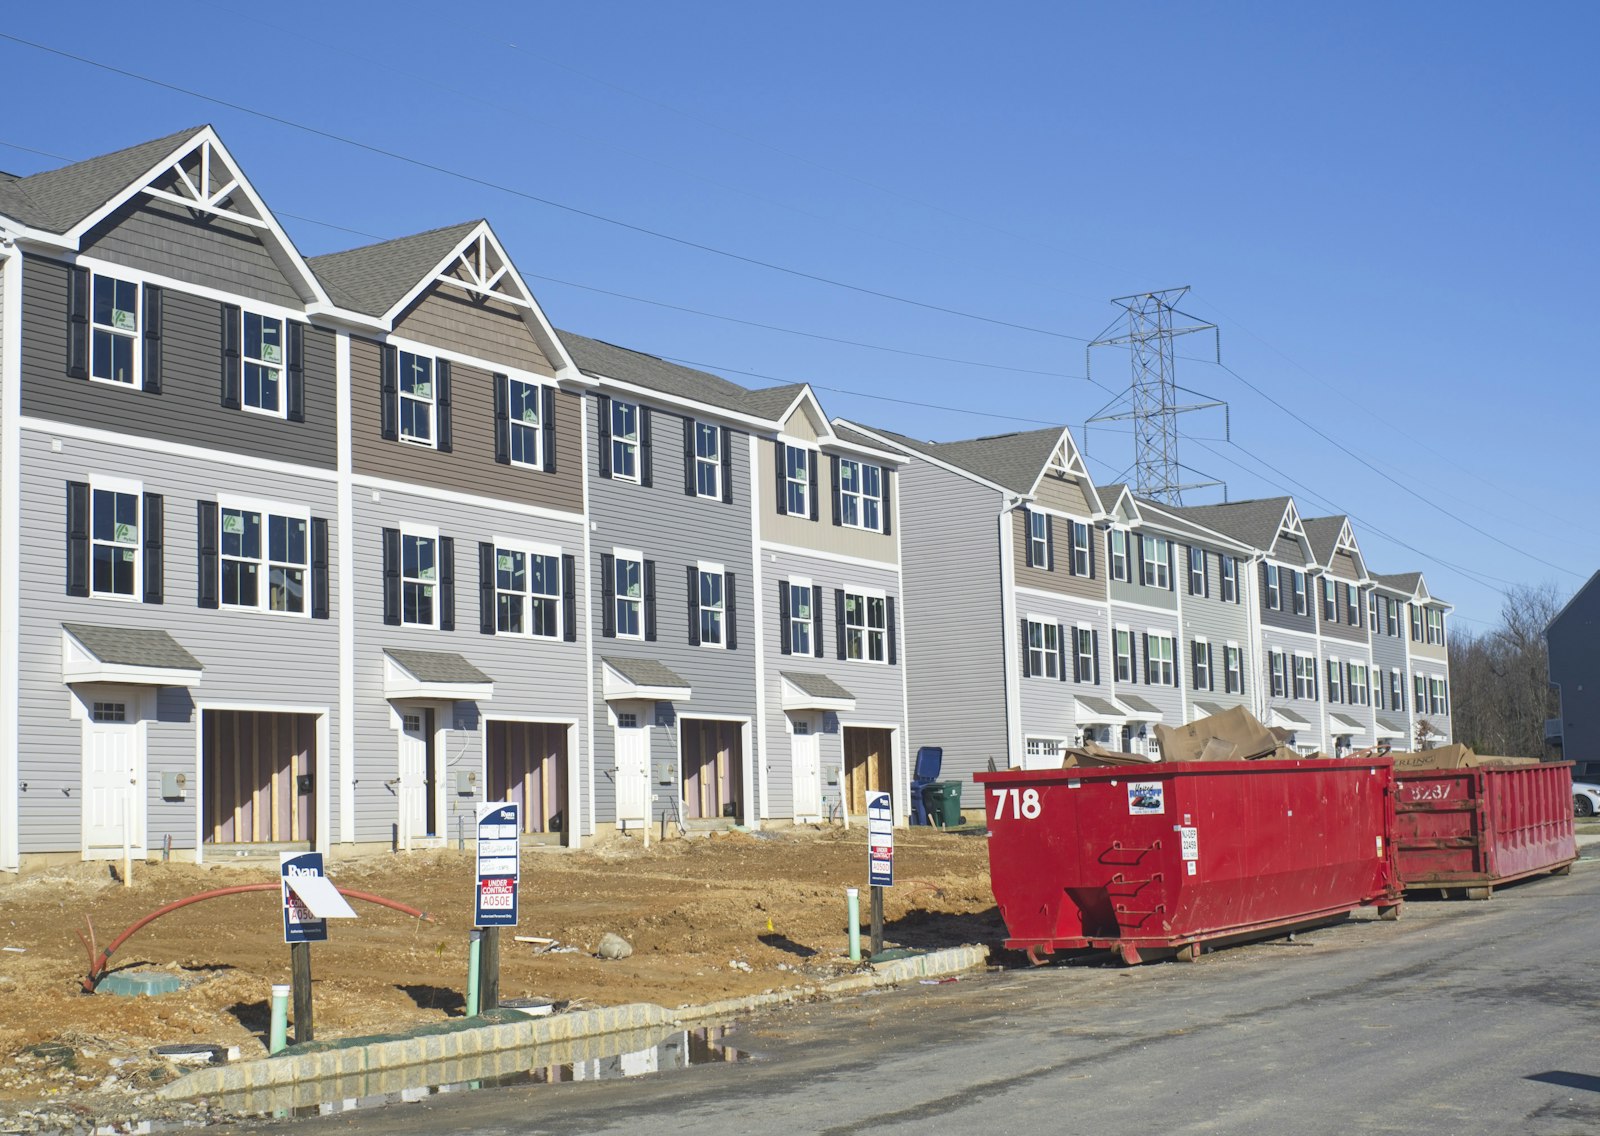
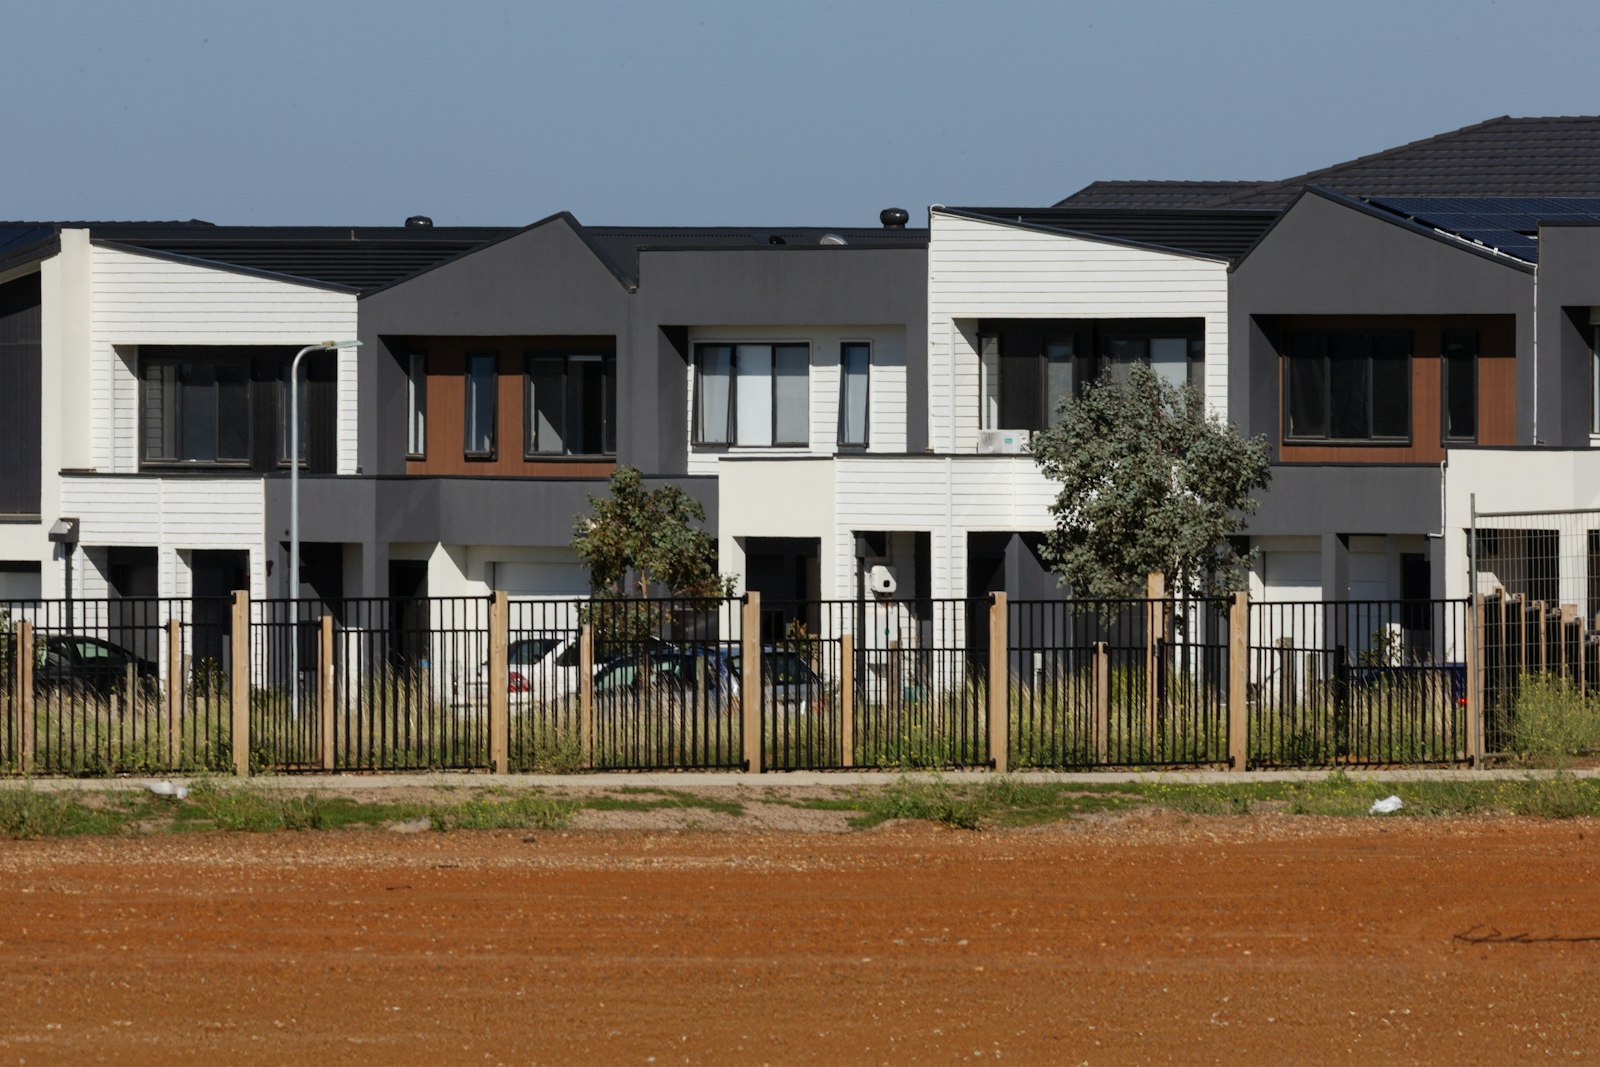
Metro Atlanta has become one of the most active build-to-rent markets in the country, and for a straightforward reason: the region adds households faster than it adds for-sale housing they can afford, and institutional and regional investors want new, professionally managed rental communities to own. Developers in Gwinnett, Cherokee, Henry, Paulding, and Cobb counties, and increasingly in the ring of exurban counties beyond them, are building horizontal apartment communities — detached homes, townhomes, and cottages on a single rental site — that never go to retail buyers. Financing that product is different from financing a for-sale subdivision, and this guide explains how Georgia BTR construction loans are structured, what Georgia law contributes, how the Atlanta submarkets compare, and how Bancaverse arranges both the construction loan and the takeout.
How is a build-to-rent construction loan different from a subdivision loan?
A traditional acquisition-and-development loan for a for-sale subdivision is repaid from lot or home sales, and the lender underwrites absorption — how many homes sell per month at what price. A BTR construction loan is repaid by a single takeout loan or sale of the whole community, so the lender underwrites the project as an income property: the stabilized rent roll, the operating expenses, the resulting net operating income, and the permanent loan that NOI will support. That shift changes everything downstream. The lender cares about rent comps rather than sale comps, about lease-up pace rather than sales pace, and about the community’s operating budget rather than a builder’s margin.
It also changes leverage. Because the exit is a loan sized to NOI rather than a series of sales, the construction lender tests the total loan against the takeout proceeds at a debt yield and coverage a permanent lender will accept. A developer who arrives with a credible takeout — a DSCR portfolio lender or an agency lender that has reviewed the plan — gets a construction loan that is faster to approve and larger relative to cost.
How does the draw process work on a Georgia BTR project?
Phase 1: land and horizontal development
The first funding covers land (or refinances a land loan), entitlements, and horizontal site work: grading, utilities, roads, stormwater, and amenities. Lenders want approved plans, a land-disturbance permit, a fixed-price or guaranteed-maximum civil contract, and evidence that the county’s water and sewer capacity is secured. Horizontal work is where budgets most often slip, so lenders scrutinize the contingency line.
Phase 2: vertical construction in draws
Vertical draws fund against inspected progress on each building or unit, typically monthly, with the lender’s inspector confirming percent complete and the developer submitting invoices and lien waivers. Many lenders fund vertical in phases — a first tranche of units delivered and leased before the next tranche starts — which reduces the interest carry and lets the lease-up validate the rent assumptions before the whole community is exposed.
Phase 3: lease-up and takeout
As units deliver, the community leases; the construction loan usually includes an interest reserve for this period. Once occupancy and NOI reach the takeout lender’s thresholds, the permanent loan repays the construction loan. Bancaverse arranges both legs so the takeout lender’s requirements — occupancy, seasoning, minimum coverage — are known at the construction closing.
Planning a build-to-rent community in metro Atlanta? Request a Georgia BTR construction and takeout sizing — send the site plan, budget, and rent comps, and Bancaverse will structure both loans across our lender bench.
What Georgia-specific rules affect construction lending?
Nonjudicial foreclosure, first Tuesday, no redemption
Georgia security deeds carry a power of sale. The lender must mail notice to the borrower at least 30 days before the sale and advertise the sale once a week for four weeks in the county’s legal organ; the sale itself takes place on the first Tuesday of the month between 10 a.m. and 4 p.m. at the courthouse, and Georgia provides no statutory right of redemption after the sale [1]. To pursue a deficiency, the lender must report the sale to the superior court within 30 days for confirmation, and the court must find the property brought its true market value [2]. For construction lenders, that combination — a fast, predictable enforcement path — is a reason Georgia collateral supports competitive leverage relative to judicial states like Ohio or Kentucky.
The 2021 lien-waiver law and draw administration
Georgia amended its lien-waiver statute, O.C.G.A. § 44-14-366, effective January 1, 2021. A signed interim or final waiver now releases only the claimant’s lien and bond rights, not its underlying contract claim, and a claimant who has not been paid has 90 days (up from 60) to file an affidavit of nonpayment to preserve its lien; filing a lien alone no longer revokes the waiver [3]. For a BTR developer, this means draw packages must track waivers and payment dates carefully, and lenders will expect a clean waiver log with every request. Bancaverse coordinates with the title company and lender’s inspector so waiver administration does not slow funding.
Water, sewer, and entitlements by county
Atlanta-metro counties differ substantially in sewer capacity, zoning tolerance for rental communities, and impact fees. Several counties have adopted or debated BTR-specific zoning categories or moratoria; lenders will ask for the approved zoning and any conditions of approval before closing. Confirming entitlements before applying is the single best way to shorten a Georgia construction closing.
How do the Atlanta-metro submarkets compare for build-to-rent?
North metro: Gwinnett, Forsyth, Cherokee
Strong school districts, employment along the GA-400 and I-85 corridors, and high for-sale prices make the north metro the deepest BTR demand pocket. Land is expensive and entitlements are contested, so projects skew toward townhomes and smaller detached homes on constrained sites. Metro Atlanta’s single-family rent is INSERT VERIFIED STAT.
South and east metro: Henry, Clayton, Rockdale, Newton
Proximity to Hartsfield-Jackson, the logistics corridor along I-75 and I-20, and lower land costs support larger detached-home BTR communities. Lenders underwrite rents conservatively here and want evidence of professional management.
West metro: Paulding, Douglas, Carroll
Fast-growing exurban counties with available land and strong owner-occupant demand that BTR can serve at a lower monthly cost than ownership. Sewer capacity is the frequent gating item.
Secondary Georgia markets: Savannah, Augusta, Columbus
Savannah’s port and manufacturing growth, Augusta’s cyber and medical base, and Columbus’s Fort Moore demand each support BTR at a smaller scale. Comp depth is thinner, so lenders lean harder on the sponsor’s track record and the takeout lender’s early review. The number of BTR units under construction in metro Atlanta is INSERT VERIFIED STAT.
| Submarket | Typical BTR product | Financing sensitivity | Likely takeout |
|---|---|---|---|
| North metro | Townhomes; small-lot detached | Land basis; entitlement timeline | Agency or DSCR portfolio loan |
| South / east metro | Detached-home communities | Rent support; management plan | DSCR portfolio loan; institutional sale |
| West metro | Detached and cottage product | Sewer capacity; absorption pace | DSCR portfolio loan |
| Savannah / Augusta / Columbus | Smaller cottage and townhome sites | Comp depth; sponsor experience | DSCR portfolio loan; regional bank |
What does a fundable Georgia BTR construction file include?
- Site control and entitlements — recorded deed or contract, approved zoning with conditions, land-disturbance permit status, and utility availability letters.
- Complete budget — land, horizontal, vertical, soft costs, interest reserve, and contingency, with a fixed-price or GMP contract for civil and vertical work.
- Rent study and operating pro forma — rent comps from professionally managed rental communities, not for-sale comps, and a management plan.
- Takeout analysis — the stabilized NOI, the permanent loan it supports, and a takeout lender that has reviewed the project.
- Sponsor and general-contractor track record — completed communities, schedule performance, and liquidity to fund cost overruns.
Developers whose construction loan is maturing before lease-up finishes should read our multifamily bridge loan guide, which covers lease-up bridge financing across Georgia and neighboring states. Investors planning a DSCR takeout on smaller BTR or scattered-site portfolios will find the underwriting framework in our DSCR loan trends guide. Both connect to the construction and takeout financing hub.
How Bancaverse arranges Georgia construction and takeout capital
Bancaverse is a private credit platform and brokerage for business-purpose mortgage lending. We do not lend our own balance sheet. We package the site, the budget, the sponsor, and the operating plan to the standard construction lenders and debt funds expect, arrange the takeout in parallel, and place the file with lenders competing for Georgia BTR. Because the construction loan is only as fundable as its exit, structuring both loans together — with the takeout lender’s thresholds written into the construction plan — is what turns a site plan into a closed construction loan.
Frequently asked questions
What is a build-to-rent construction loan?
A short-term loan that funds land, horizontal site work, and vertical construction of a rental community in inspected draws, repaid by a permanent loan or sale once the community is built and leased.
How is BTR underwritten differently from a for-sale subdivision?
The lender sizes the loan to the stabilized rental income and the takeout it supports rather than to lot or home sales, so rent comps, operating expenses, and the permanent lender’s requirements drive the numbers.
What is Georgia’s foreclosure process on a construction loan?
Georgia allows nonjudicial foreclosure under a power of sale: 30 days’ notice to the borrower, four weeks of advertisement, a first-Tuesday courthouse sale, and no post-sale redemption; a deficiency requires court confirmation within 30 days [1][2].
How did Georgia’s 2021 lien-waiver change affect construction draws?
Waivers now release only lien and bond rights, and unpaid claimants have 90 days to file an affidavit of nonpayment [3]. Lenders expect accurate waiver logs with every draw request.
Can I get a construction loan without a takeout lined up?
Sometimes, but leverage and approval speed improve substantially when a takeout lender has reviewed the project. Bancaverse arranges the takeout alongside the construction loan for that reason.
What takeout options exist for a completed Georgia BTR community?
Common exits include a DSCR portfolio loan across all homes, an agency loan where the community qualifies, a bank or life-company permanent loan, or a sale to an institutional owner.
How long does a Georgia BTR construction loan run?
Terms generally cover the construction schedule plus lease-up, often 24 to 36 months with extension options tied to completion and occupancy milestones.
Bancaverse™ can help you get private capital for your commercial real estate project. Here are the links to schedule a call or apply: Schedule a call · Apply now
Sources & references
- Nolo, “Georgia Foreclosure Laws, Timeline, and Homeowner Rights” — 30-day notice, four weeks’ advertisement, first-Tuesday sale, no post-sale redemption. https://www.nolo.com/legal-encyclopedia/georgia-foreclosure-laws-procedures.html
- O.C.G.A. § 44-14-161, Sales made on foreclosure under power of sale; when deficiency judgment allowed; confirmation and approval. https://law.justia.com/codes/georgia/2022/title-44/chapter-14/article-7/part-1/section-44-14-161/
- NCS Credit, “Georgia Lien Waivers: Changes Coming 2021” — O.C.G.A. § 44-14-366 amendments effective Jan 1, 2021; 90-day affidavit of nonpayment. https://www.ncscredit.com/education-center/blog/georgia-lien-waivers-changes-coming-2021
- Reviewer to add source URLs for each INSERT VERIFIED STAT (metro Atlanta single-family rent; BTR units under construction) — suggested: Zillow Observed Rent Index, John Burns Research, RealPage, or Yardi Matrix BTR report.